Table of Contents
A rental application form asks for a number: monthly income. Proof of income is the paperwork that backs that number up. For landlords, knowing exactly what counts, and what doesn’t, is the difference between signing a lease with confidence and discovering a rent shortfall three months in.
This guide walks through the documents landlords in Canada and the US commonly accept, how the list changes for employed, self-employed, and other-income applicants, and how to check that what’s in front of you is genuine rather than just plausible.
Key Takeaways
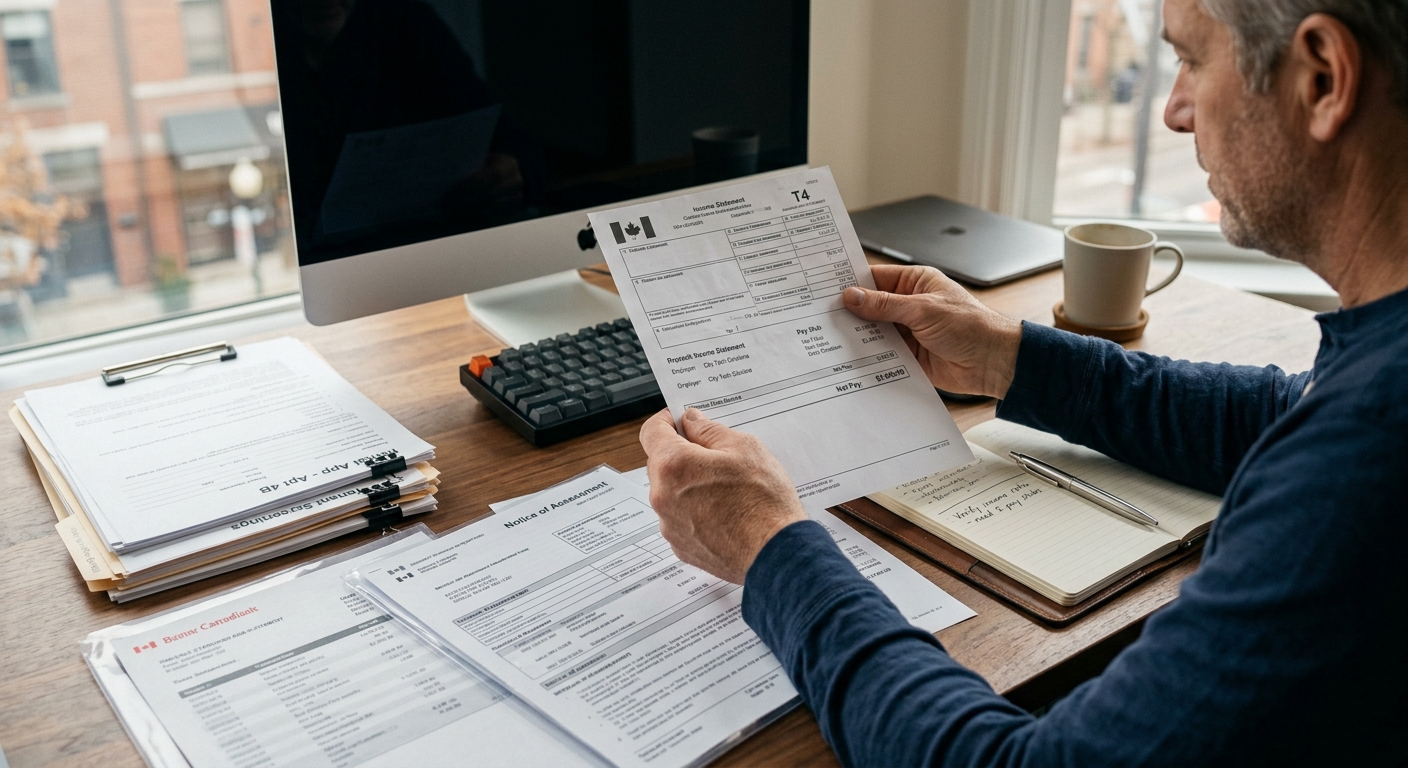
- Pay stubs, an employment letter, and a T4 (or W-2 in the US) cover most employed applicants, typically two to three recent pay stubs plus one supporting document.
- Self-employed and gig-economy applicants can’t provide pay stubs. A CRA Notice of Assessment or Proof of Income Statement, 12–24 months of bank statements, or invoices fill that gap.
- A document only counts as proof if it’s verifiable: dated, naming the applicant and (where relevant) the employer, and consistent with the rest of the application.
- Income documents should be reviewed alongside credit history and rental history, not as a stand-alone qualifier, to stay aligned with human rights and fair-housing guidance.
What “Proof of Income” Actually Means
Proof of income is a verifiable, typically third party-issued document that confirms how much an applicant earns and where that money comes from. A number typed into an application form isn’t proof․ it’s a claim.
Proof of Income for Employed Applicants
For salaried or hourly employees, three document types cover almost every case:
| Document | What It Shows | How Many to Request |
| Pay stubs | Gross/net pay, pay frequency, employer name | 2–3 most recent |
| Employment letter | Position, salary, length of employment | 1, on letterhead |
| T4 (Canada) / W-2 (US) | Prior year’s total employment income | Most recent tax year |
Proof of Income for Self-Employed and Gig-Economy Applicants
Self-employed applicants, freelancers, and gig workers don’t have pay stubs, so the documentation shifts:
- A CRA Notice of Assessment or Proof of Income Statement (sometimes called an “Option C printout”), an official summary of reported income, available through the applicant’s CRA My Account.
- 12–24 months of business or personal bank statements showing consistent deposits.
- Invoices or a T2125 (Statement of Business or Professional Activities) for Canadian sole proprietors.
- In the US, the equivalent documents are 1099 forms and filed tax returns.
Proof of Income for Other Income Sources
Not every applicant’s income comes from a job. Common alternatives include:
- Pension, retirement, or disability benefit letters.
- Court-ordered support payment documentation.
- Investment of income or rental income statements from other properties.
A compliance note: where income comes from social assistance or another public benefit, treat that documentation the same way you would an employment letter. Source-of-income protections mean this category of income cannot be weighted differently, or held to a stricter standard, than employment income.
Figure 1: Common proof-of-income documents by how an applicant earns.
Verifying Proof of Income — Not Just Collecting It
Collecting a document isn’t the same as confirming it’s accurate. A few consistency checks catch most problems:
- Confirm the applicant’s name, employer, and dates match across every document submitted.
- Call the employer directly using a number you find independently, not one printed in the letter itself.
- Compare deposits on bank statements against the income stated on pay stubs or an employment letter.
- Be cautious of documents with inconsistent fonts, misaligned figures, or math that doesn’t add up: common signs a pay stub has been edited.
Let Verification Happen Automatically
A Royal Invest tenant credit check verifies income and pulls real bureau credit data in one report, so nothing rests on eyeballing a pay stub or chasing an employer by phone.
Run a Tenant Credit Check
How Proof of Income Connects to the Income-to-Rent Ratio
Every proof-of-income document ultimately feeds into one calculation: the income-to-rent ratio, which most landlords use as a first-pass affordability filter. A verified document supports a reliable ratio; an unverified number supports a guess.
What Landlords Should Avoid Asking For
Collect only what’s needed to verify income. Full Social Insurance Numbers or Social Security Numbers, banking passwords, or full account numbers are rarely necessary for income verification and increase privacy risk if that data is ever exposed. Staying within PIPEDA and, in Quebec, Loi 25 means collecting the minimum information required for the purpose and storing it securely.
How Royal Invest Takes the Guesswork Out of This
Most landlords aren’t document-forensics experts, and they shouldn’t have to be. Spotting a doctored pay stub, cross-checking dates across three different documents, and independently confirming an employer all take time, and a landlord juggling a handful of units, on top of everything else, is exactly who is most likely to skip a step under pressure. That’s usually not carelessness; it’s simply that manual verification doesn’t scale well against a full-time job and a life outside it.
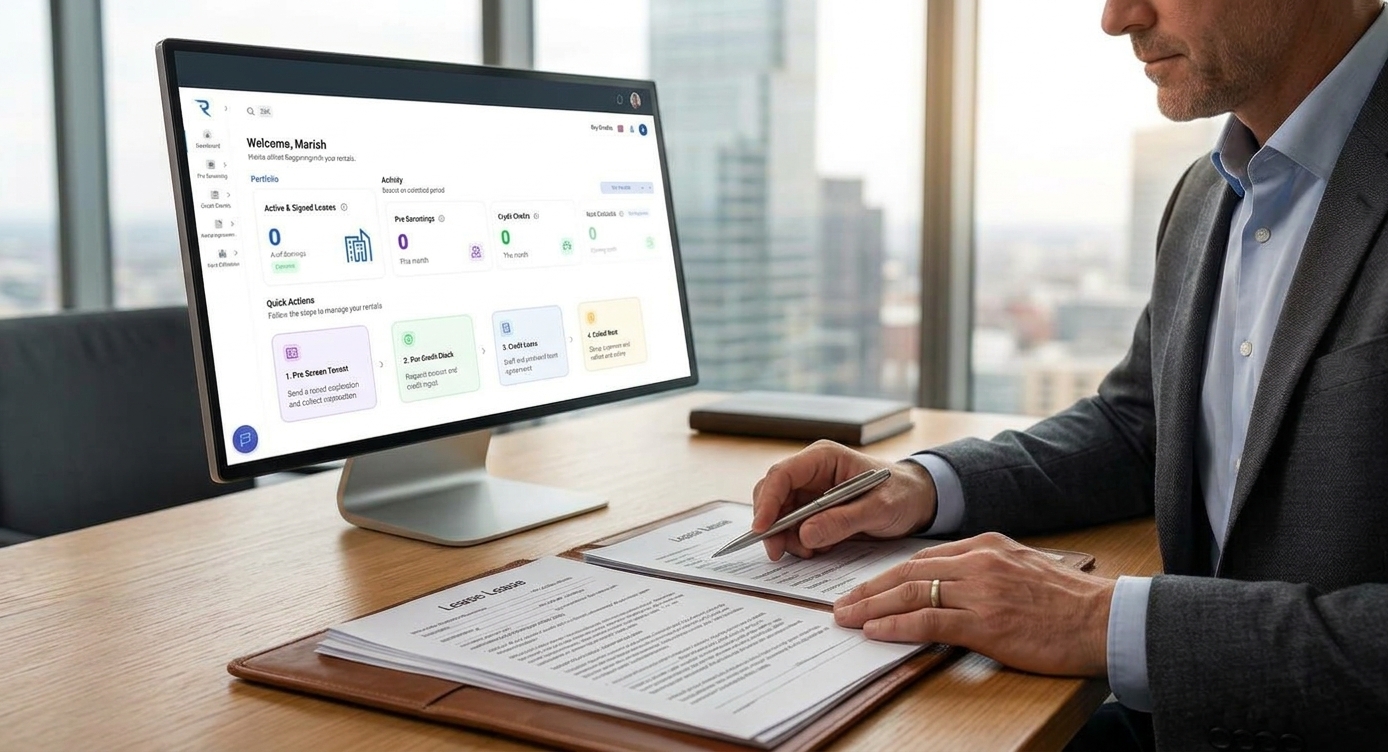
A RoyalInvest tenant credit check folds income verification into the same report used for the credit pull, so it isn’t a separate task competing for attention. Real bureau data comes back alongside the applicant’s information, and the tenant receives the consent request directly, no chasing documents by email, no account required on their end. Rather than eyeballing a pay stub and hoping it holds up, a landlord gets a plain-language risk level and a clear PASS/FAIL recommendation, with income and credit weighed together, in minutes.
That consistency matters as much as the convenience: every applicant gets the same verification process, which is a meaningfully better safeguard than a quick manual glance that varies from one application to the next. Run one from the RoyalInvest tenant credit check page, and once income and credit both check out, move directly into an official lease agreement on the same platform.
Frequently Asked Questions
What documents count as proof of income for renting an apartment?
Most commonly, landlords accept two to three recent pay stubs, an employment letter on company letterhead, and a prior-year T4 or W-2. Self-employed or gig-economy applicants typically substitute a Notice of Assessment or Proof of Income Statement, 12–24 months of bank statements, or invoices, since they can’t produce a standard pay stub to begin with.
Can a landlord ask for a Notice of Assessment?
Yes. It’s an official CRA-issued document, which makes it one of the most reliable ways for self-employed or variable-income applicants to confirm reported annual income when pay stubs don’t exist. Applicants can retrieve it, or the similar Proof of Income Statement, through their CRA My Account in a few minutes, at no cost.
How many pay stubs should a landlord request?
Two to three of the most recent, consecutive pay stubs is standard practice, enough to confirm the income is current, consistent, and not a one-off bonus period. Requesting significantly more than that isn’t usually necessary for verification purposes and can raise avoidable privacy concerns under PIPEDA or, in Quebec, Loi 25.
What if a tenant is self-employed with no pay stubs?
Request a Notice of Assessment or Proof of Income Statement alongside 12–24 months of bank statements. Together, they show both what was officially reported to the CRA and the actual cash flow moving through the applicant’s accounts, particularly useful for gig workers or freelancers whose monthly income fluctuates.
Is a bank statement enough proof of income on its own?
Not usually. A bank statement confirms that deposits happened, but not their source, so it can’t distinguish rental income, a loan, or a one-time gift from genuine employment earnings. Pairing it with an employment letter, pay stub, or Notice of Assessment gives a verifiable picture of both the amount and where it comes from.
Resources
Leave a Reply